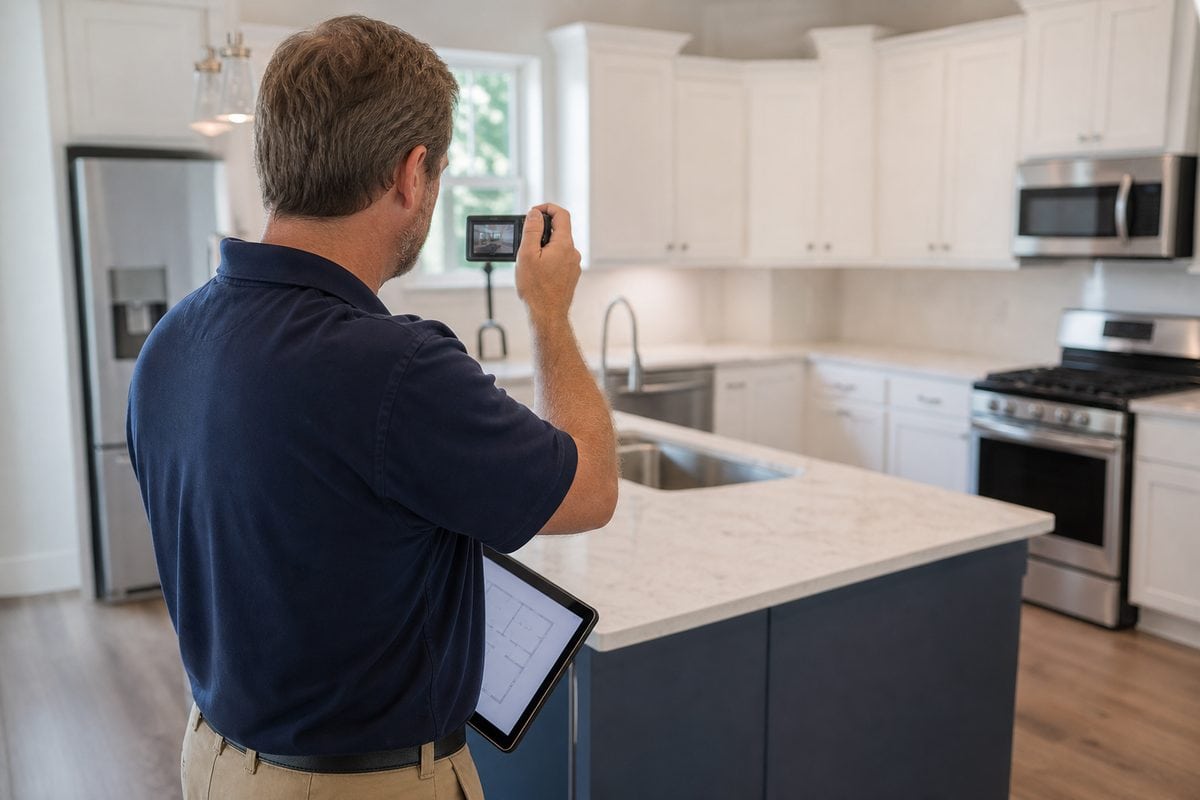
What do appraisers look for? Three things, on behalf of the lender: what exactly this property is, what condition it is in, and what comparable homes have actually sold for. The visit is a measured, photographed inventory of the house, and the report compares that inventory to recent closed sales. Your taste, your furniture, and your asking price are outside the frame.
I wrote this for three readers who type the same question. The Houston buyer whose lender just ordered the appraisal and who is worried it won’t come in at the contract price. The homeowner refinancing who wants to know what the appraiser will open, measure, and photograph. And the seller who has read my home appraisal checklist and wants the framework behind it. The first half applies to all three of you; the loan-type sections near the end are where the answer changes.
The three questions an appraiser is answering
Every residential appraisal report is organized around the same three questions. What is it? The site, the structure, the room count, the living area, the garage, the pool, the age. What shape is it in? A condition rating and a quality rating, with the defects that drove them written down. What have similar homes sold for? Closed sales, adjusted for the differences, that support the value. Everything the appraiser does during the visit feeds one of those answers.
Since it comes up: I’m a licensed Texas real estate broker and I also hold a Texas Certified Residential Appraiser license. That appraisal work is done for lenders, and I never appraise a property I’m involved with as a real estate agent or real estate broker. The framework below is simply the one the report itself uses.
What do appraisers look for during the walk-through?
There is a required list, and it is the same list whether the house is spotless or lived-in. The exterior is photographed from the front, rear, and street, with the lot, drainage, fences, and any outbuildings noted, because the appraiser is confirming that the house on the ground matches the public record and the survey. The kitchen, every bath, the main living areas, and any defect or update are photographed so the underwriter can see the condition the rating describes. The exterior is measured and the living area calculated under the ANSI Z765-2021 standard, which Fannie Mae has required since April 1, 2022.
The bedroom and bath count is confirmed by the appraiser’s standard for size, egress, and access, which is why a study with no egress window stays a study. The attic hatch, water heater, electrical panel, and furnace or air handler are looked at, and the report says whether access was possible. The systems and the roof are described, with any visible defect recorded by feature and location. Additions and conversions are described, and where the work was done without a permit, Fannie Mae’s guidelines ask the appraiser to comment on its quality and its effect, if any, on value.
Houston adds a wrinkle to the measurement. Converted garages and enclosed patios are everywhere in our older subdivisions, and under the ANSI standard they count as living area only when they are finished to the same standard as the rest of the house and reached from inside it; finished space reached only through unfinished space is reported separately. The second wrinkle is permits. The City of Houston and the City of Katy permit remodels and conversions, while much of unincorporated Harris County permits new structures, garages, fill, and floodplain work, so a 1990s garage conversion in Cypress may have no permit trail at all. The appraiser describes what is there and lets the comparable sales show what buyers pay for it.
How condition and quality are rated
Fannie Mae’s appraisal standards grade condition on a six-point scale and construction quality on a matching one. C1 is new and never occupied, C2 is like-new, C3 is well maintained with only minimal wear, C4 is adequately maintained with moderate wear, C5 shows significant wear from inadequate maintenance, and C6 is a home with damage or deferred maintenance severe enough to affect its safety, soundness, or structural integrity. Quality runs from Q1 for an individually designed custom home to Q6 for a structure that may not meet local building standards. The full definitions are in the Selling Guide section on property condition and quality of construction.
For the typical Houston resale, the line that matters sits between C3 and C4, and what moves a home across it is deferred maintenance: the roof near the end of its life, the water stain nobody traced, the rotted trim, the HVAC that limps along. Fannie Mae’s guidance says minor conditions such as worn floor finishes, worn carpet, or a small plumbing leak must be reported and do not need to be repaired for the loan to close. A home rated C5 is still eligible as is, provided the deficiencies do not affect safety, soundness, or structural integrity. A C6 rating is the exception: the appraisal has to be made subject to the repairs that bring the home to at least C5.
The report format is changing this fall, and it changes how condition is written up. Fannie Mae and Freddie Mac’s redesigned appraisal report, UAD 3.6, opened to lenders on January 26, 2026, and on November 2, 2026 it becomes the required format for appraisals delivered to them, with a lender exception window that runs to May 19, 2027. The C and Q scales stay the same. The interior and the exterior now get their own condition and quality ratings, and each defect the appraiser notes becomes its own entry: which feature, where in the house, what the problem is, whether safety, soundness, or structural integrity is affected, and what the appraiser recommends. The reference guide is on Fannie Mae’s Uniform Appraisal Dataset page, and the list of what is worth fixing before the visit lives in the checklist post linked at the top.
How the comps get picked
The comparable sales carry the value, and the appraiser chooses them by plain rules. They are closed sales; a pending contract or an active listing can support the value and nothing more. They are recent, physically similar in size, age, style, and condition, and from the same market area, which in Houston is a street-level idea. The same floor plan in the same subdivision can sit in two different MUD districts with two tax rates, two elementary attendance zones, and two flood histories, and buyers pay differently on each side of those lines. A good appraiser keeps the comparables on the subject’s side of the line wherever the data allows.
If you have read my post on how real estate agents price homes in Houston, the method will look familiar, because a careful listing price is built from the same closed sales. The appraiser is working for the lender, and every adjustment has to be supported in the report, line by line, for an underwriter who has never seen the house. (Earlier in the process and wondering what the house is worth at all? Start with how a CMA compares with a Zestimate.)
The same rule governs the professionals at the table. Under the valuation-independence rule in Regulation Z, 12 CFR §1026.42, lenders and settlement-service providers, real estate agents among them, may not influence the value through coercion, inducement, or intimidation, and Fannie Mae’s appraiser independence requirements say no one may attempt to influence the result. What the rule allows is just as specific: anyone may ask the appraiser to consider additional, appropriate information about the property, including comparable sales, and to correct a factual error. The buyer, the seller, and the real estate agents can all supply facts. None of them can supply a number.
What do FHA appraisers look for?
On an FHA loan, the appraiser does the same inventory and the same comparison, then applies HUD’s minimum property requirements. The standard is that the home must be safe, sound, and sanitary, and the specifics are in HUD Handbook 4000.1, most recently updated August 12, 2026. On Houston resales, the items that come up most often are these:
- Defective paint on a home built before 1978: peeling or chipping paint has to be corrected, because the handbook treats defective paint on those homes as a lead hazard.
- The roof: it has to keep moisture out and have at least two years of life left, and a new stain on a ceiling is usually what leads an FHA appraiser to ask for a roofer’s opinion.
- Active water intrusion: a leaking supply line or water coming through a wall or roof is a condition item until it is fixed.
- Working, safe systems: the appraiser runs the heating, cooling, plumbing, and electrical systems, and exposed or frayed wiring the appraiser can see is written up as a deficiency.
- Wood-destroying insects: visible evidence of termites or other wood-destroying insects makes the appraisal subject to a pest inspection.
Missing handrails and cracked window glass sit on the other side of the line: both are generally treated as cosmetic under HUD’s handbook and under Fannie Mae’s guidance, so they get reported without a repair requirement. A rail that wobbles on an open staircase can still be written up as a safety item, which is why I tell sellers to fix it anyway.
What do VA appraisers look for?
A VA appraisal follows the same three questions and then applies VA’s minimum property requirements from Chapter 12 of the VA Lender’s Handbook (Pamphlet 26-7). The headline standard matches FHA’s: safe, structurally sound, and sanitary. The roof must keep moisture out and provide reasonable future utility, mechanical systems must be safe to operate, and a home built before 1978 is presumed to have lead-based paint, so any defective paint in it has to be corrected. VA’s Change 46 to the handbook, effective for appraisals ordered on or after May 1, 2026, took a few things off the list: defective paint on a home built in 1978 or later is now treated as cosmetic, and detached sheds and similar outbuildings no longer have to meet the property standards.
The Texas-specific item is the termite report. The Houston area sits in the highest termite-probability zone on the map VA uses, so a VA purchase appraisal here requires a wood-destroying insect inspection report. Since VA Circular 26-22-11 (June 15, 2022), the veteran buyer is allowed to pay for that inspection, which removed an old sticking point in Texas negotiations; the contract decides who actually does. The rest of the program is in my guide to VA loans in Houston, and current circulars are posted on VA’s home loan circulars page.
What do appraisers look at for a refinance?
The same things. The inspection, the measurement, the photographs, and the comparable sales are identical to a purchase appraisal, because the lender is asking the same three questions about the same collateral. The context is what changes. There is no contract price to anchor to, so the value stands on the closed sales alone. No real estate listing agent meets the appraiser, so you provide the access and answer the questions. And a refinance appraiser has no listing description to work from, so a one-page list of what you have done, with the month and year and the cost, is the single most useful thing you can hand over. Describe the new roof, show the invoice, and let the report arrive at its own number.
What “subject to” and “as is” mean on the report
Most appraisals are made as is: the value is stated for the property in its current condition, and minor items are reported without a requirement. The alternatives are the ones that move a closing date. Subject to completion means the home isn’t finished yet, which is common on new construction. Subject to repairs or alterations means a specific item has to be fixed before the loan can close, which is what happens with a C6 rating on a conventional loan or a minimum property requirement on an FHA or VA loan. Subject to inspection means the appraiser saw something that needs a licensed professional’s opinion, such as foundation movement, roof damage, or termite evidence.
When a repair condition is placed, the lender needs proof it was done, usually a re-inspection by the appraiser documented on a completion report, though Fannie Mae lets the lender accept other satisfactory evidence of the correction in some cases. The re-inspection carries a fee, and who pays it is negotiated between buyer and seller. When the required repair cannot be finished by the closing date, the parties sometimes close anyway with an escrow holdback for the work, if the lender allows it. A conditioned appraisal is one of the items the underwriter clears before final approval, which I walk through in my post on how long underwriting takes. If the value itself comes in under the contract price, the buyer’s options under the Third Party Financing Addendum are a separate subject, covered in my post on the financing contingency.
What appraisers are not looking at
The furniture and the decor are outside the report; the appraiser photographs the room, not the sofa. Your asking price, and the number the deal needs, are not inputs. The neighbor’s active listing is a listing, and at most it is a supporting indicator. And an appraisal is not a home inspection: outlets are not tested one by one, and a check that the systems operate says nothing about their remaining life.
How I help my clients through the appraisal
For buyers, my work starts when the report arrives. I read it the way the underwriter will: the comparable sales and the adjustments, the condition rating and the defects behind it, and any subject-to language that will show up as a loan condition. If the value is under the contract price, we go through the options under Paragraph 2B of the financing addendum together before anyone makes a call. For sellers, the preparation is the checklist, and on the day I meet the appraiser with one folder of facts: the dated improvement list, any permits, the survey and warranties, and the closed sales I relied on when we priced the home. What I say to the appraiser is the information Regulation Z allows, and nothing more.
Whoever you hire, you can judge how a real estate agent handles appraisals with a few questions. What do you hand the appraiser, and what do you say? Which closed sales did you use, and would an appraiser agree with them? If the value comes in under the contract price, what are my options that week? A capable real estate agent answers all three specifically. The rest of that interview is in my guide on how to choose a real estate agent, and you can see how I work with Houston sellers and what I cover with buyers on my mortgage information page.
Appraisal questions, answered
What do house appraisers look for in a home?
What the property is, what condition it is in, and what comparable homes have sold for. The visit covers the measurement, the photographs, the bedroom and bath count, the attic, garage, and mechanical systems, and any defect recorded by feature and location; the value then comes from recent closed sales of similar homes nearby, adjusted for the differences.
Do appraisers look in closets, attics, and garages?
Yes. The garage is measured and photographed, the attic hatch is opened to confirm access and look for visible problems, and closets matter because a bedroom has to meet the appraiser’s standard for size, egress, and access to be counted as one. The appraiser is confirming what those spaces are and what condition they are in, and has no interest in what is stored there.
Does clutter or furniture affect an appraisal?
Not as a rating input. Condition is about the structure, the finishes, and the systems, and furnishings never enter the rating. Clutter hurts indirectly when it blocks the attic, the water heater, or the electrical panel, or hides a floor or wall the appraiser needs to see, so clear the paths and let the house show its condition.
What do appraisers look for when refinancing?
The same things as on a purchase. What differs is the context: there is no contract price to compare against and no listing description to work from, so the most useful thing a homeowner can do is provide access and hand over a dated list of improvements with their costs.
What is the difference between an appraisal and an inspection?
An inspection is for you and answers what is wrong with the house, system by system. An appraisal is for the lender and answers what the house is, what condition it is in, and what it is worth, using the comparable sales. An appraiser notes visible defects and whether systems operate, a narrower look than an inspector takes, and on an FHA or VA loan also checks the home against that program’s minimum property requirements.
Do appraisers know the contract price?
On a purchase, yes. The lender provides the contract, and the report analyzes it, including any seller concessions. The value still has to be supported by the comparable sales, and federal valuation-independence rules bar the lender and the settlement-service providers, real estate agents included, from trying to influence the result.
Have an appraisal coming up?
Buying, selling, or refinancing in the Houston area, from Cypress to Katy, and want to talk through what the appraiser will see before the visit, or what the report means after it? I’m glad to walk through it with you. There’s no pressure and no obligation.
Schedule a Consultation
Call or Text (281) 500-7077
Kevan Pewitt · REALTOR® & Broker · Houston Prime Realty
Last updated: October 2026 · Appraisal standards summarized from Fannie Mae’s Selling Guide (B4-1.3) and UAD 3.6 materials, HUD Handbook 4000.1 (August 12, 2026 update), VA Pamphlet 26-7 Chapter 12 (Change 46, effective May 1, 2026) and VA Circular 26-22-11, and Regulation Z §1026.42, as of October 2026. General information, not legal or lending advice.
More on this topic: mortgages and financing in Houston →
